Exploring the Diverse Landscape of Mortgages: A Comprehensive Guide
The mortgage market is a vast and complex ecosystem, offering a wide array of options tailored to meet diverse financial needs and preferences. When embarking on the journey of homeownership, it's crucial to understand the different types of mortgages available. This guide will delve into the various mortgage types, their unique features, and the scenarios they cater to.
Fixed-Rate Mortgages: Steady as She Goes
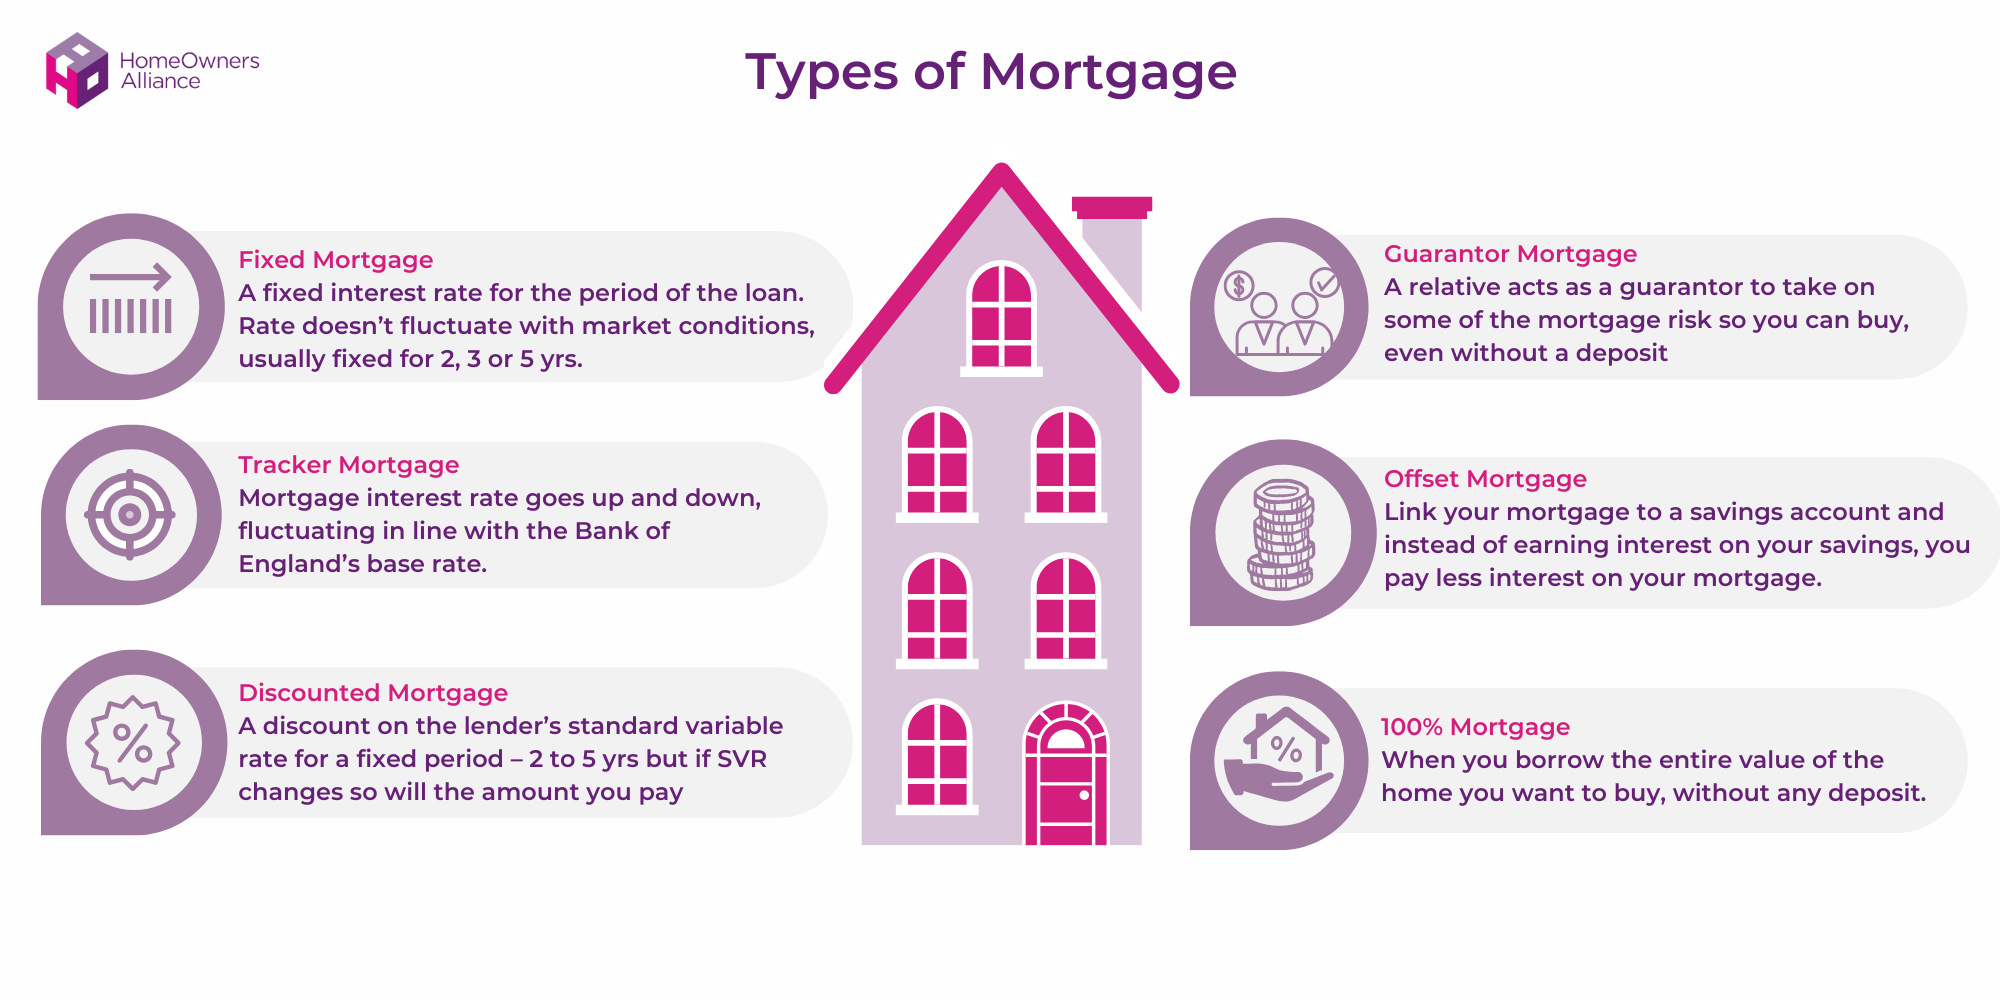
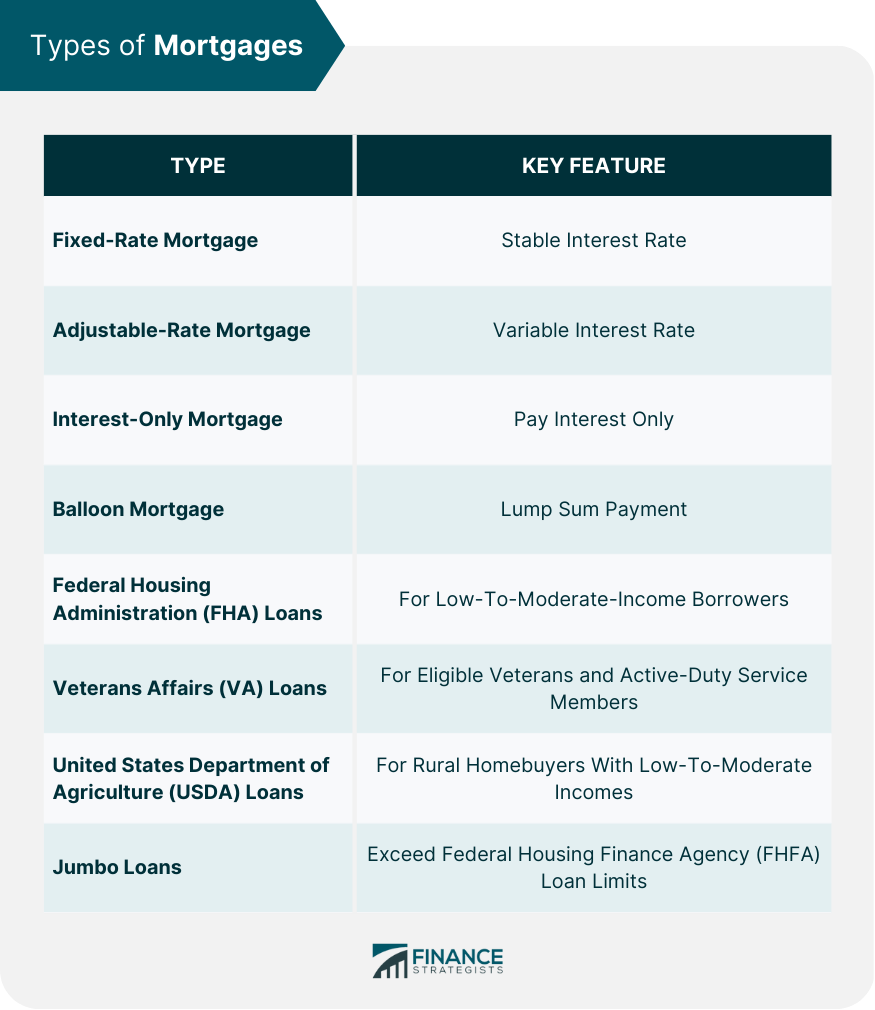
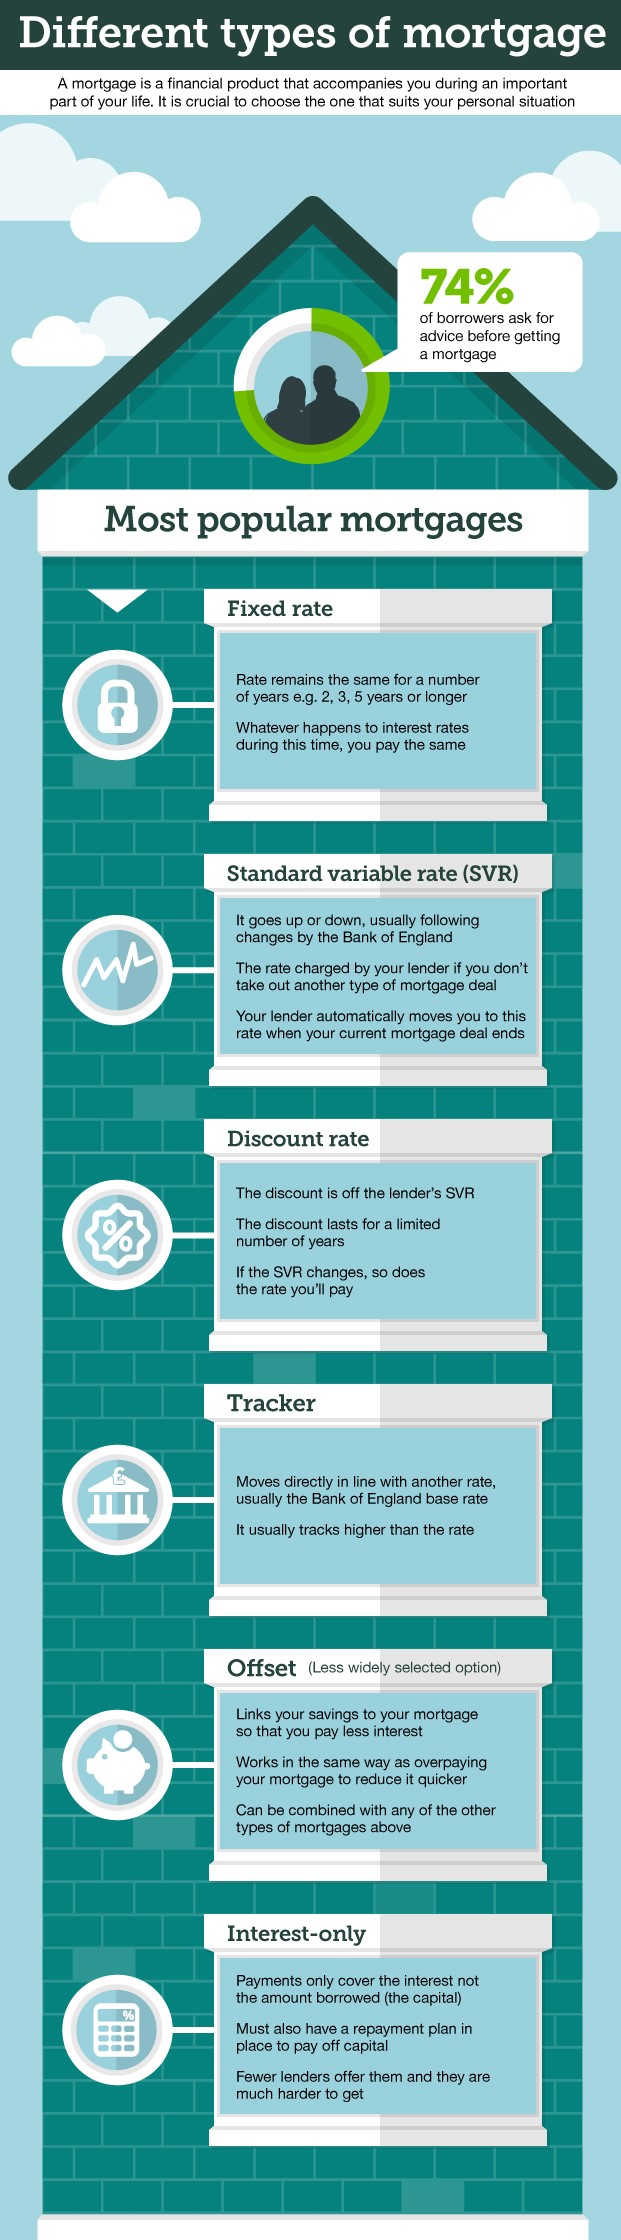
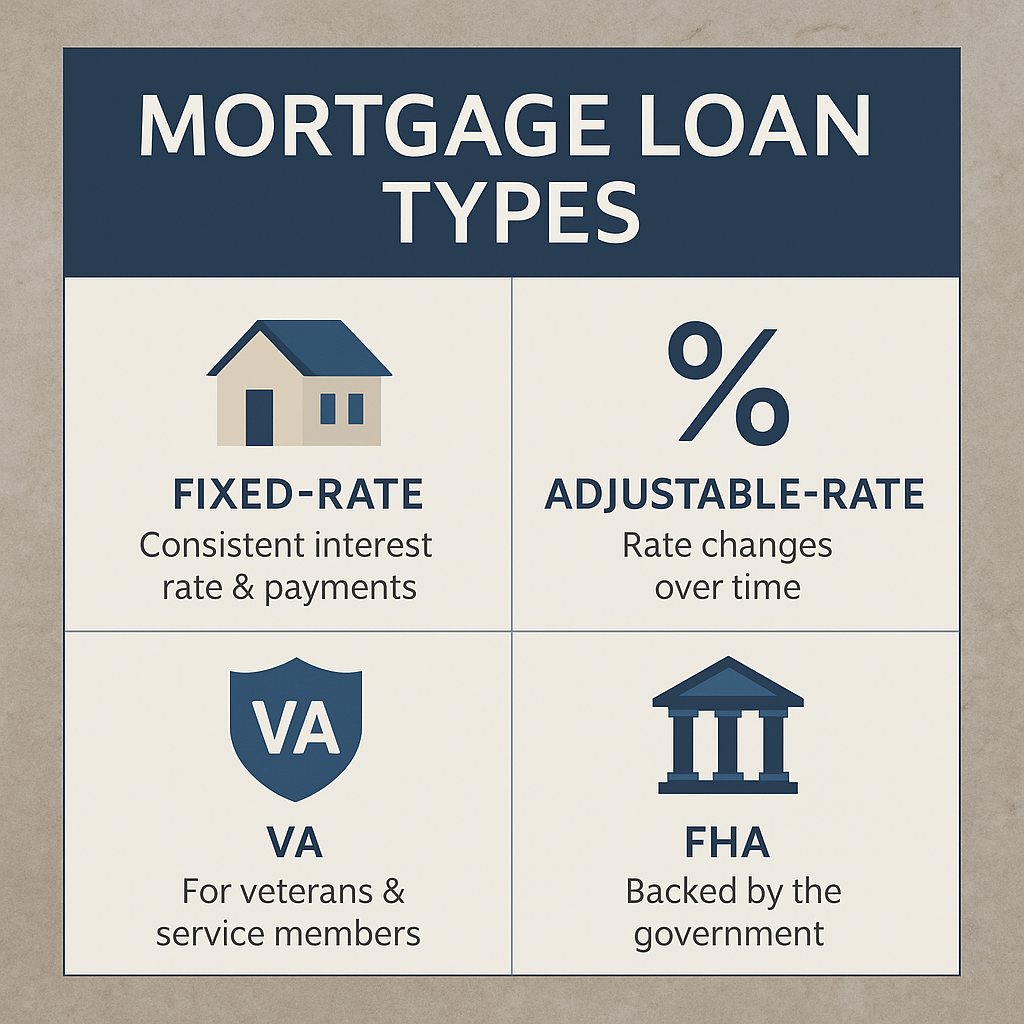
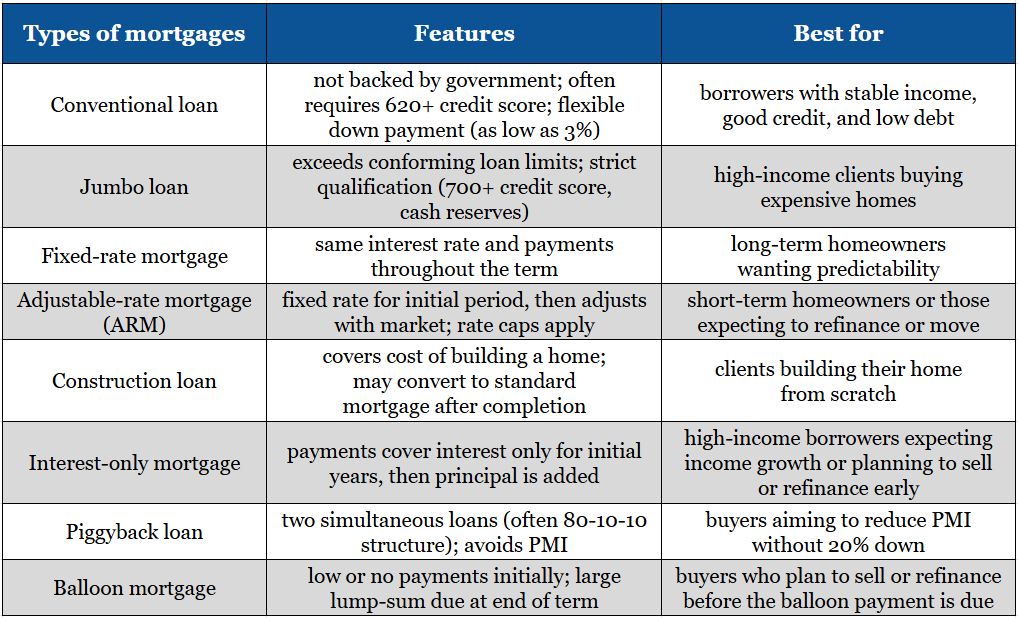
Fixed-rate mortgages are the most common type, offering borrowers the predictability of a consistent interest rate and monthly payment over the loan's life. This consistency is particularly appealing to those who prefer the stability of knowing exactly what they'll pay each month, regardless of market fluctuations. Fixed-rate mortgages typically come with terms ranging from 10 to 30 years.
15-Year Fixed-Rate Mortgages
15-year fixed-rate mortgages offer a shorter repayment term, resulting in significant interest savings over the loan's life. However, they come with higher monthly payments compared to their 30-year counterparts. This option is ideal for homeowners who can afford the higher payments and want to build equity faster.
30-Year Fixed-Rate Mortgages
30-year fixed-rate mortgages provide lower monthly payments, making them an attractive option for those with limited budgets or who prefer to keep more cash on hand. While they do come with higher interest costs over the loan's life, their predictability and affordability make them a popular choice among homeowners.
Adjustable-Rate Mortgages (ARMs): Flexibility with a Catch
Adjustable-rate mortgages (ARMs) offer an initial fixed-rate period, typically ranging from 5 to 10 years, after which the interest rate adjusts annually based on market conditions. ARMs often start with lower interest rates than fixed-rate mortgages, making them an appealing option for those who plan to move or refinance before the initial fixed period ends. However, they come with the risk of increasing payments if interest rates rise.
Hybrid ARMs
Hybrid ARMs combine features of fixed-rate and adjustable-rate mortgages, offering an initial fixed-rate period longer than that of a traditional ARM. After the fixed period, the interest rate adjusts annually. These mortgages can be an excellent fit for homeowners who want the stability of a fixed-rate mortgage for a set period but are open to the potential benefits of an ARM.

Government-Backed Mortgages: A Helping Hand
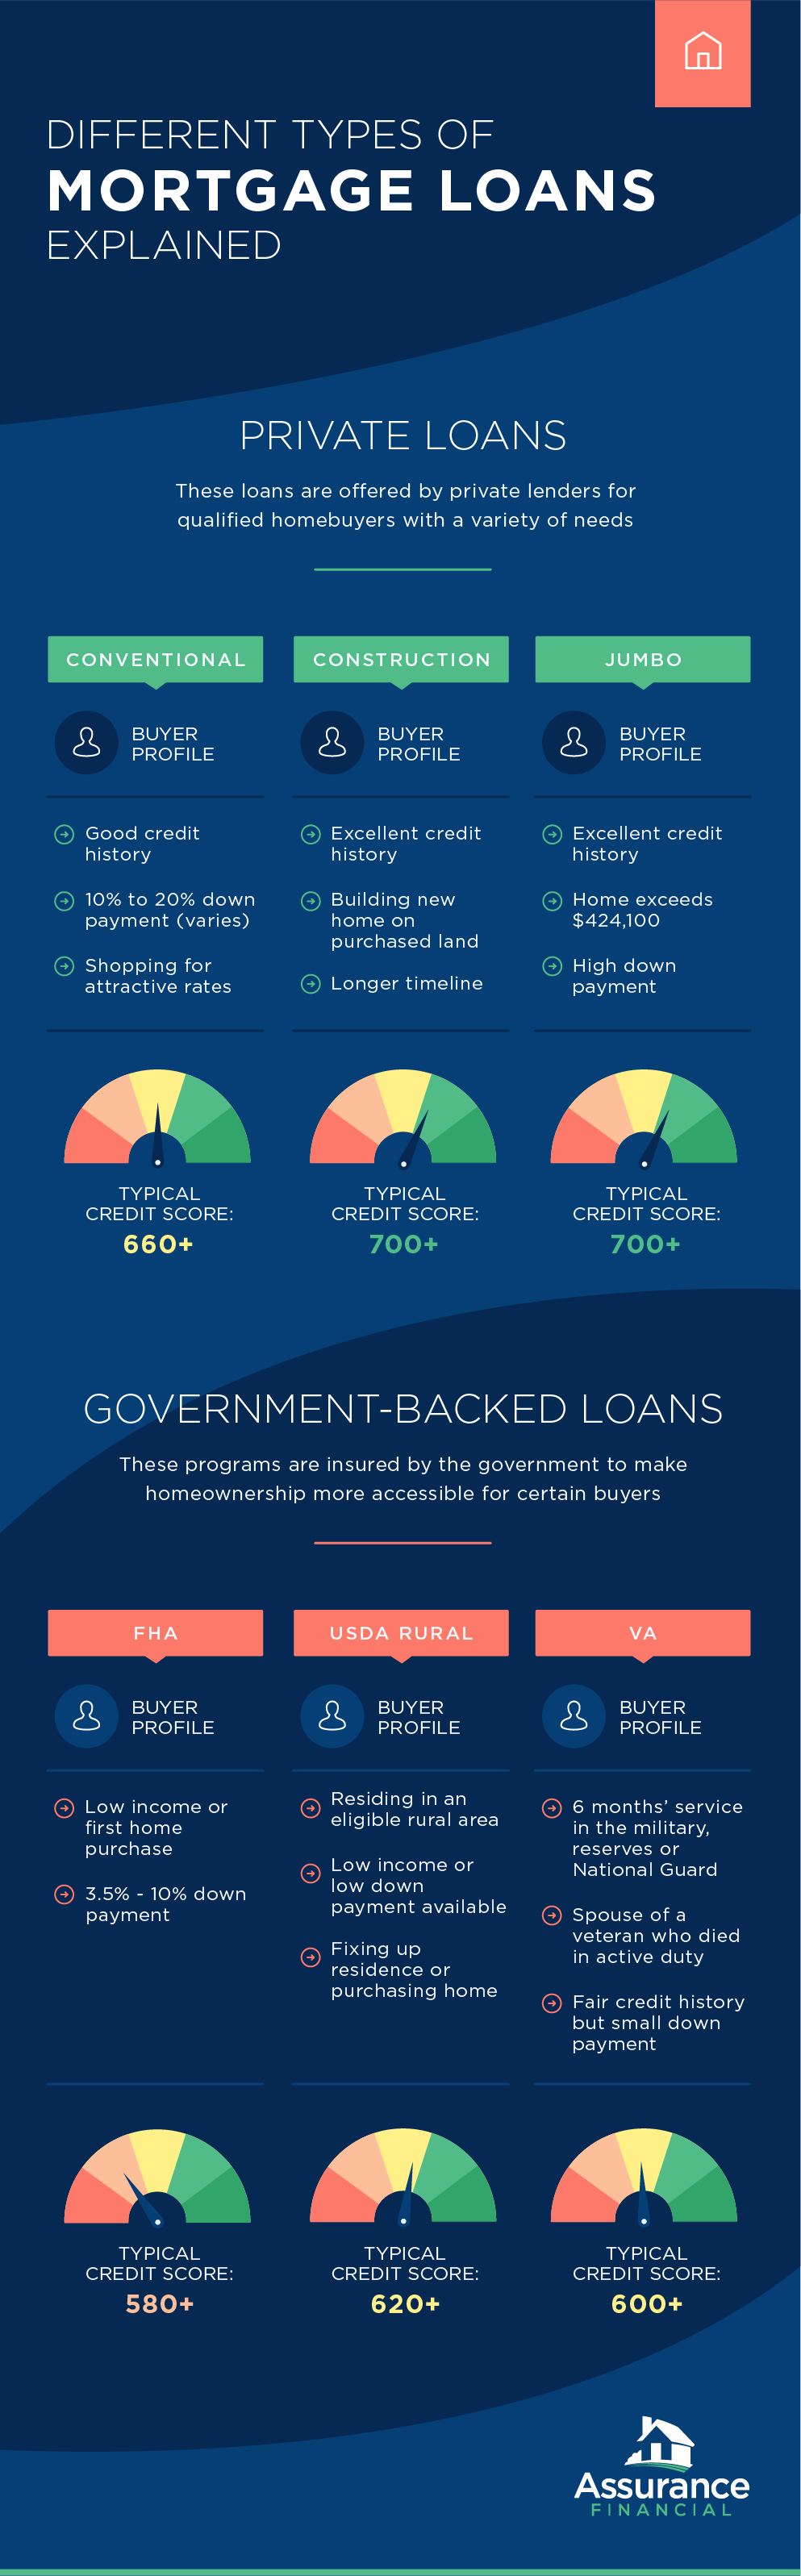
Government-backed mortgages are designed to help low- to moderate-income borrowers and those with limited savings afford homeownership. These loans are backed by government entities, reducing lenders' risk and allowing them to offer more favorable terms.
FHA Loans
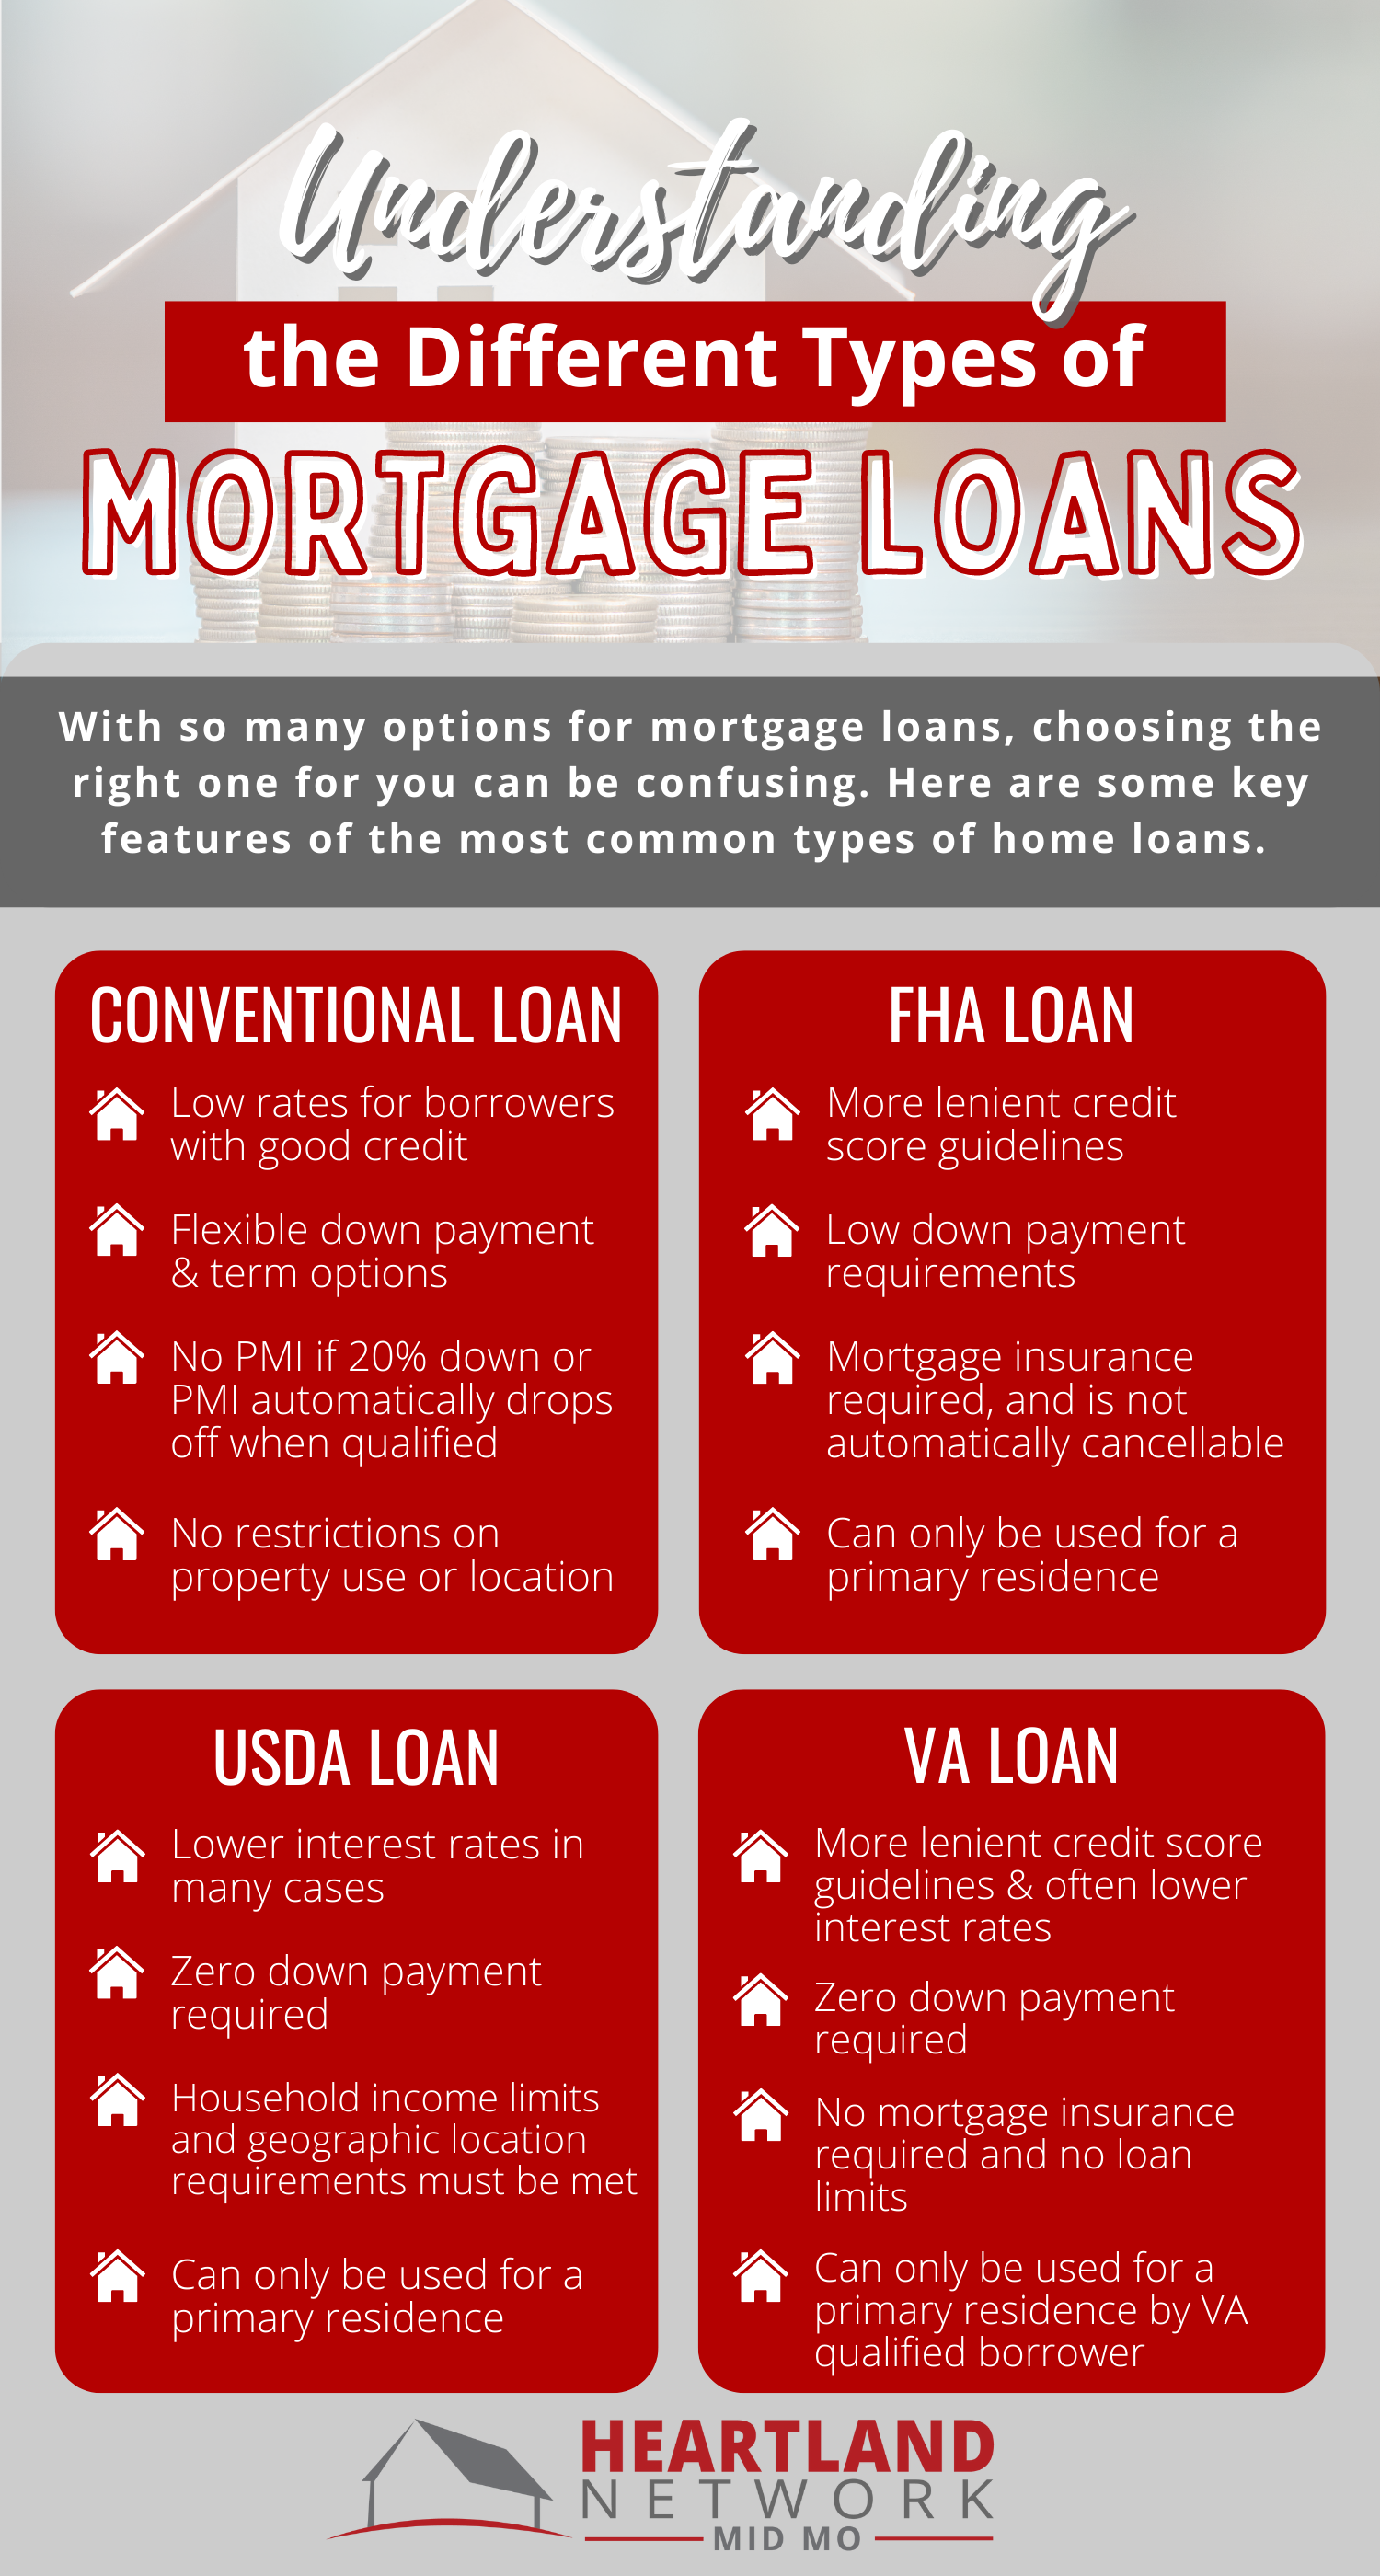
FHA loans, backed by the Federal Housing Administration, require lower down payments and credit scores than conventional mortgages. They are an excellent option for first-time homebuyers or those with limited savings. However, they do come with mortgage insurance premiums, which can increase monthly payments.
VA Loans
VA loans, guaranteed by the U.S. Department of Veterans Affairs, are available to eligible military personnel, veterans, and their families. They offer no down payment and no private mortgage insurance requirements, making them a popular choice among eligible borrowers.
USDA Loans
USDA loans, backed by the U.S. Department of Agriculture, are designed for low- to moderate-income borrowers purchasing homes in rural areas. They offer no down payment and low interest rates, making homeownership more accessible to those in eligible locations.
Jumbo Loans: Thinking Big
Jumbo loans are non-conforming mortgages that exceed the conforming loan limits set by the Federal Housing Finance Agency. These loans are typically used to purchase high-value homes and may come with more stringent underwriting requirements and higher interest rates than conventional mortgages.
Choosing the Right Mortgage: A Personal Decision
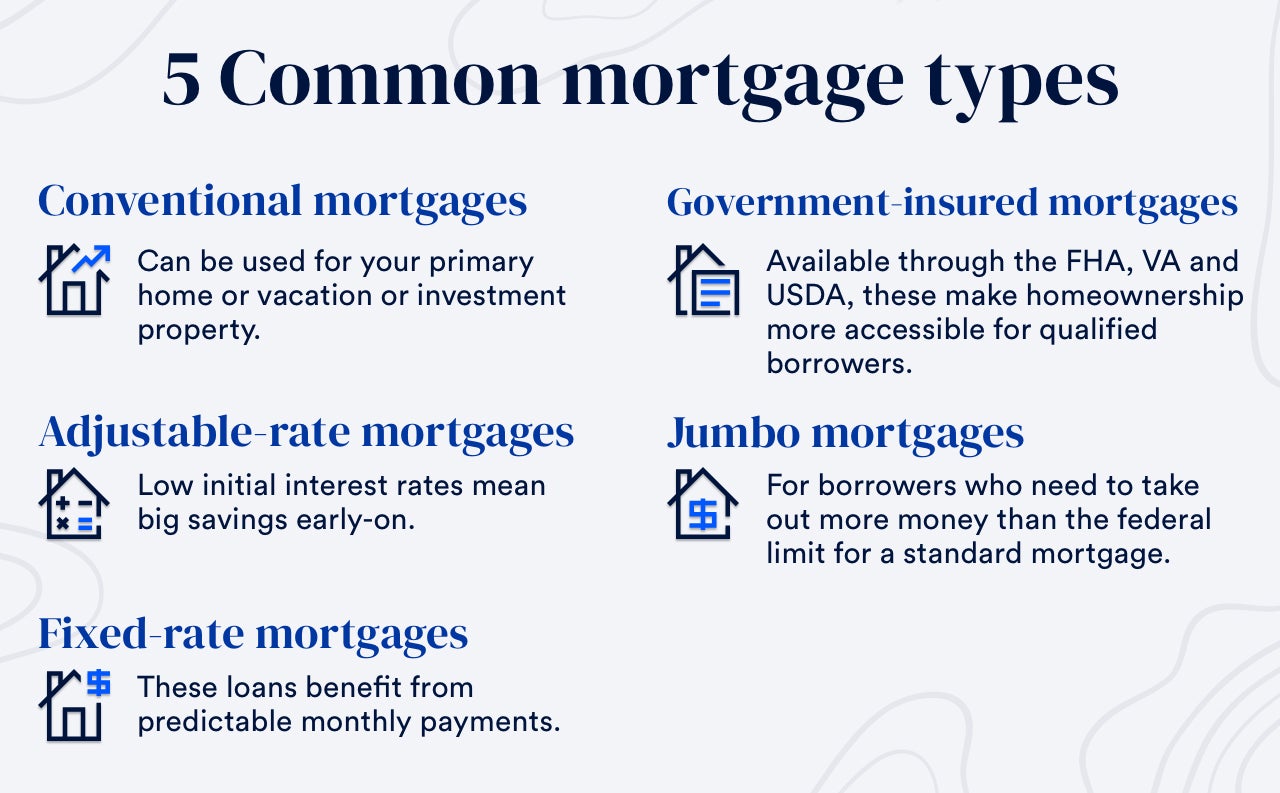
When selecting a mortgage, it's essential to consider your financial goals, budget, and risk tolerance. Fixed-rate mortgages offer predictability, while ARMs provide flexibility. Government-backed mortgages can help those with limited savings afford homeownership, and jumbo loans cater to high-value properties. By understanding the various mortgage types and their unique features, you can make an informed decision that sets you on the path to successful homeownership.